Inheriting an Apartment: Whether to Keep or Sell - Criteria, Procedures, and Deadlines
Emi Tokudomi (licensed real estate broker, 宅地建物取引士)Acquisitions
21 min read
When inheriting an apartment from a parent, many people initially struggle with whether to continue managing the rental business or sell the property. Since there are tenants, you cannot simply leave it unattended, and deadlines for inheritance tax filing and registration overlap.
This article organizes the decision criteria for whether to keep or sell an inherited apartment and the important deadlines for procedures after inheritance. Deadlines for taxes and registration are confirmed based on guidance from the National Tax Agency and the Ministry of Justice, specifying the confirmation date. Estimated selling prices are calculated from Urbalytics' listing data (last 12 months, excluding duplicate listings).
Key points of this article
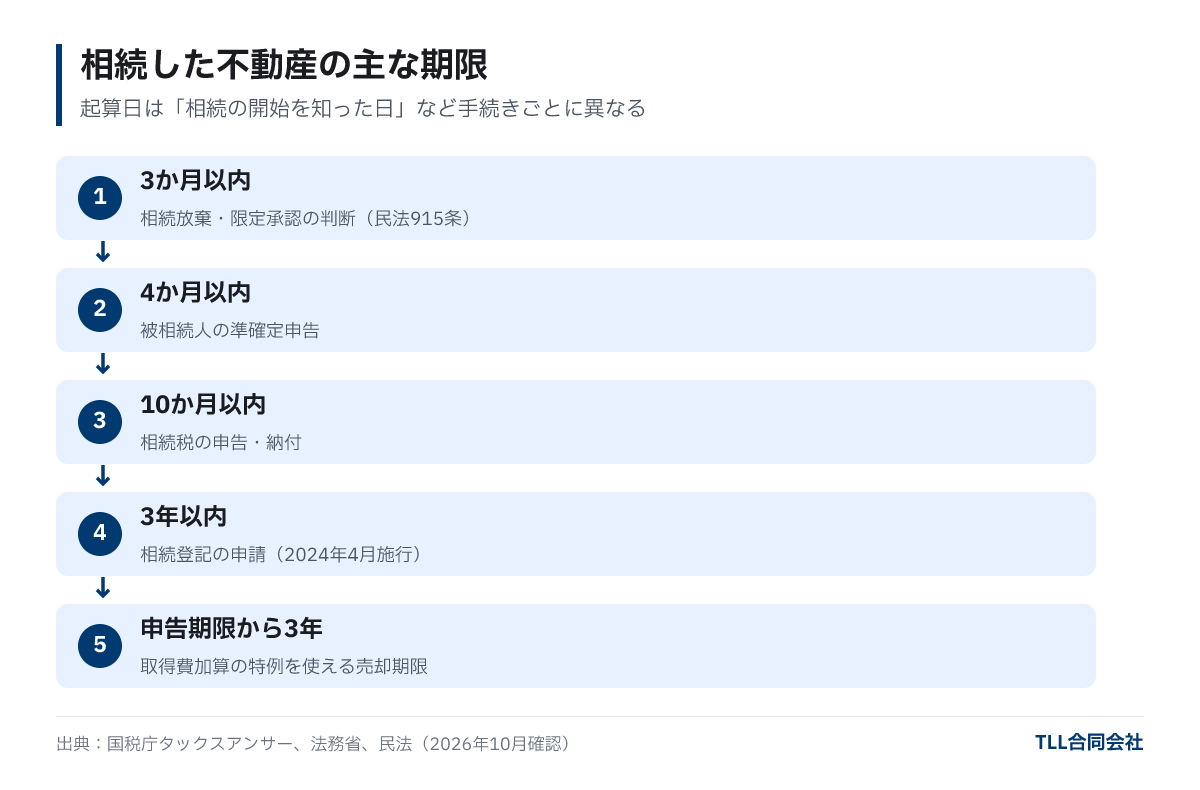
- Different procedures with varying deadlines overlap for inherited real estate: renouncing inheritance (within 3 months), filing a quasi-final tax return (within 4 months), inheritance tax filing and payment (within 10 months), and inheritance registration (within 3 years from the day the acquisition is known, effective April 1, 2024) (Civil Code Article 915, National Tax Agency and Ministry of Justice, confirmed October 2026).
- If a person who paid inheritance tax sells the property within three years after the day following the inheritance tax filing deadline, part of the paid inheritance tax can be added to the acquisition cost, reducing capital gains tax (National Tax Agency Tax Answer No. 3267, as of April 1, 2026 law and regulations).
- Dividing annual rent of 6 million yen by the median gross yield of whole-building listings at each station yields approximate values of around 125 million yen in Akabane (4.80%), 100 million yen in Funabashi (6.00%), and 97 million yen in Machida (6.19%) (Urbalytics, October 2025 - October 2026, 34-44 listings per station).
Procedures and Deadlines for Inherited Apartments
First, list the procedures with deadlines, then decide whether to keep or sell. Note that the starting date for deadlines differs for each procedure.
| Procedure | Deadline | Legal basis / Source |
|---|---|---|
| Renunciation of inheritance / limited acceptance | Within 3 months from the day the person knows inheritance has started for themselves | Civil Code Article 915 (e-Gov, confirmed October 2026) |
| Quasi-final tax return of the deceased | Within 4 months from the day after the day the person knows inheritance has started | National Tax Agency Tax Answer No. 2022 |
| Inheritance tax filing and payment | Within 10 months from the day after the day the person knows the decedent died | National Tax Agency Tax Answer No. 4205 (as of April 1, 2026 law and regulations) |
| Inheritance registration application | Within 3 years from the day the person knows they acquired real estate by inheritance. For inheritances before April 1, 2024, deadline is March 31, 2027 | Ministry of Justice "Mandatory inheritance registration" (confirmed October 2026) |
| Selling using the special rule of acquisition cost addition | From the day after inheritance starts until three years after the day following the inheritance tax filing deadline | National Tax Agency Tax Answer No. 3267 (as of April 1, 2026 law and regulations) |
Sources: Civil Code, National Tax Agency Tax Answer, Ministry of Justice website, compiled by TLL. Confirmation date: October 2, 2026.
If inheritance registration is not applied for within the deadline without justifiable reason, a penalty of up to 100,000 yen may be imposed. If inheritance division is not agreed upon, one heir may apply for "heir declaration registration" to fulfill the obligation within the deadline. Note, however, that inheritance registration based on inheritance division is ultimately necessary to sell.
Criteria for Whether to Keep or Sell
The starting point is "who can keep the property, with how much effort, and how much net income can be secured?" Checking the following five points will clarify the direction.
- Income and expenses: From rent rolls and repayment schedules, calculate the net yield deducting vacancy losses, management fees, repairs, and fixed asset tax. If there is remaining debt, confirm whether group credit life insurance is in place.
- Repair plans: If exterior walls, rooftop waterproofing, or plumbing are due for renewal soon, spending from several million to tens of millions of yen is expected. Be especially cautious with older properties lacking repair histories.
- Management personnel and effort: Who handles tenant relations and repair decisions? If living far away or busy with a main job, include management outsourcing fees in the budget (Management outsourcing and asset management).
- Inheritance tax payment funds: If cash is lacking and paying inheritance tax requires selling, estimate the time required and work backward from the 10-month deadline.
- Number and intention of heirs: With multiple heirs holding shared ownership, consensus is needed on selling or large repairs (explained later).
When keeping the property, note that to use the special deduction for small-scale residential land (rental business land up to 200㎡, 50% reduction), the rental business must be continued and the land held through the inheritance tax filing deadline (National Tax Agency Tax Answer No. 4124). Selling before the deadline disqualifies this deduction. If uncertain, compare the tax reduction from the special rule versus benefits of early sale before deciding timing.

Price Estimates When Selling (Based on Yield by Station)
The inheritance tax valuation (based on road price or fixed asset tax value) used for tax filing does not match the actual selling price. When considering selling, check how much buyers would pay as an income property. The price of a whole-building apartment is estimated by dividing the annual rent by buyers’ desired yield.
| Station | Listings | Yield 25% Low / Median / 25% High | Price Estimate for 6 Million Yen Annual Rent (Median) | Range (Calculated from 25% High to 25% Low Yield) |
|---|---|---|---|---|
| Akabane | 34 listings | 4.22% / 4.80% / 6.58% | Approx. 125 million yen | Approx. 91.19 million to 142.16 million yen |
| Funabashi | 44 listings | 5.18% / 6.00% / 6.53% | Approx. 100 million yen | Approx. 91.89 million to 115.93 million yen |
| Machida | 40 listings | 5.57% / 6.19% / 7.33% | Approx. 96.92 million yen | Approx. 81.83 million to 107.75 million yen |
Source: Urbalytics listing data. Listings and price changes from October 2, 2025 to October 2, 2026 for whole-building properties (excluding duplicate listing across sites, excluding gross yields below 1% or above 25%). Gross yield = listed rent ÷ listing price. Listing price, not transaction price. Data compiled October 2, 2026.
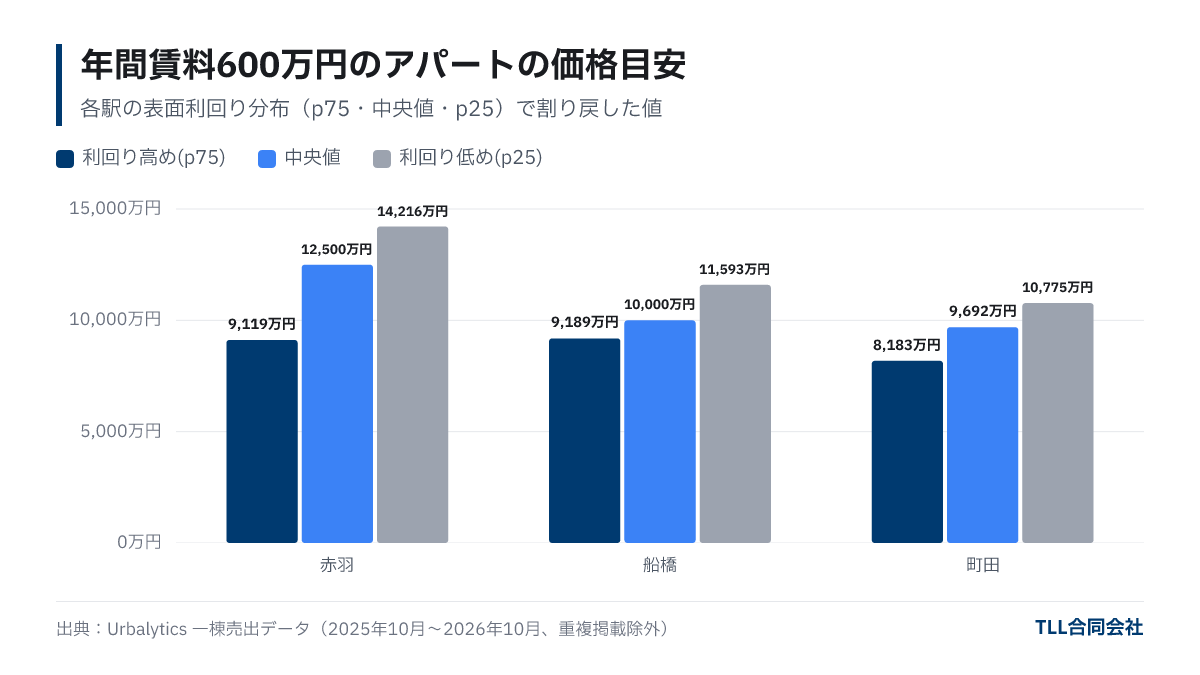
Inheriting apartments is often of older vintage, so they tend to appear in the higher yield (lower price) 25% range. For how to sell properties with difficulties such as non-rebuildable land or leasehold rights, see Selling Non-Rebuildable, Leasehold, and Inherited Old Apartments.
Taxes to Know When Selling: Acquisition Cost Addition and Ownership Period Transfer
When selling an inherited apartment, capital gains tax applies on the profit at ordinary income tax and resident tax rates. There are two inheritance-specific rules.
Acquisition cost and ownership period transfer from the decedent
The acquisition cost is calculated based on the purchase price and fees paid by the decedent, and the ownership period is also inherited from the decedent (National Tax Agency Tax Answer No. 3270, as of April 1, 2026 law and regulations). If the parent held the property for a long time, the sale soon after inheritance qualifies for long-term capital gains tax rate (20.315%). However, the acquisition cost of the building is often small due to depreciation, so capital gain tends to be large. Please refer to Depreciation and Tax on Sale for details on the calculation method.
Special rule of acquisition cost addition for inheritance tax
If the person who paid inheritance tax sells within the deadline, part of the paid inheritance tax corresponding to the sold property can be added to the acquisition cost. The addition amount = "their inheritance tax amount × (inherited tax valuation amount of sold property ÷ total acquired property value)" but the addition amount cannot exceed the capital gain (National Tax Agency Tax Answer No. 3267).
For example, if the inheritance tax amount is 12 million yen, the total acquired property value is 200 million yen, and the apartment’s inheritance tax valuation is 60 million yen, then the addition amount is 12 million yen × 60 million yen ÷ 200 million yen = 3.6 million yen. At a long-term capital gains rate of 20.315%, this reduces tax by about 730,000 yen (estimate including special reconstruction income tax). Confirm eligibility and exact amount with a tax accountant.

Notes on Shared Inheritance
If inheritance division is not agreed on and siblings or others inherit as co-owners, later selling and management decisions become difficult. The Civil Code requires unanimous consent of co-owners for acts that significantly change the form or utility of shared property (modifications), and management matters can be decided by the majority of co-owners’ shares by value (Civil Code Articles 251 and 252, e-Gov, confirmed October 2026). Rental contracts can be set by majority shareholders for periods not exceeding three years.
- To sell the entire property, unanimous agreement of all co-owners is necessary. Selling just your share is possible but limits buyers and tends to reduce price compared to whole-property sales.
- Rental income distribution: According to a Supreme Court precedent (Sept 8, 2005), rent generated before inheritance division is concluded is acquired by heirs according to their statutory shares. Early decision is recommended on who manages rent and how expenses are settled.
- Inheritance division period: After 10 years from inheritance start, division considering special benefits or contributions generally cannot be made (Civil Code Article 904-3).
If co-ownership seems likely, consider selling and dividing cash (partition by sale) or one heir acquiring the property with compensation paid to others (partition by compensation) at the inheritance division stage to reduce later hassle.

Frequently Asked Questions
Q. Can I sell without doing inheritance registration?
No. To transfer ownership to the buyer, inheritance registration into the heir’s name must be completed first. "Heir declaration registration" fulfills the registration obligation but is not a transfer of title for sale.
Q. Can I sell before filing inheritance tax?
You can sell, but the special deduction for small-scale residential land (rental business land) requires holding through the tax filing deadline, so it cannot be applied. Compare tax benefits and reasons for early sale to decide.
Q. Until when can the special rule of acquisition cost addition be used?
You must sell between the day after inheritance and within three years after the day following the inheritance tax filing deadline. Those not liable for inheritance tax cannot use this rule (National Tax Agency Tax Answer No. 3267).
Q. Can I sell with tenants in place?
Yes. Selling with tenants is called "owner change," where the rental contract and security deposit obligations transfer to the buyer. You do not need tenants to vacate.
Summary
- After inheritance, multiple overlapping deadlines exist: renouncing inheritance (3 months), filing quasi-final tax return (4 months), inheritance tax filing (10 months), and inheritance registration (3 years) (confirmed October 2026).
- Whether to keep or sell depends on income and expenses, repair plans, management, tax payment funds, and heirs’ intentions. The special deduction for small-scale residential land requires holding until the filing deadline.
- Selling within three years after the inheritance tax filing deadline can allow reduced capital gains tax via acquisition cost addition.
- Price estimates for an apartment with 6 million yen annual rent vary by station: approx. 125 million yen in Akabane and 97 million yen in Machida. Check actual prices with a free appraisal.
Featured image (Image): Photo: Luke Paris / Unsplash
About this article
- Author
- Emi Tokudomi(Acquisitions)Qualifications: Real Estate Transaction Agent
Handles investment property acquisitions and the review of documents and operating figures, drawing on experience in rental management, brokerage and sales support. She has more than 18 years of practical real estate experience and now works on acquisitions at TLL. With Japan's Real Estate Transaction Specialist qualification and bookkeeping knowledge, she considers management and repair costs alongside property income, as well as the documents needed for a transaction. Her articles explain gross versus net yield, purchase costs, financing fundamentals and purchase procedures for foreign nationals. She emphasizes distinguishing advertised yields from the cash left after expenses and identifying what to verify before buying. Her management and brokerage experience informs acquisition assessments that also consider operations after purchase.
View profile → - Publisher
- TLL合同会社宅地建物取引業 東京都知事(1)第108202号住宅宿泊管理業 国土交通大臣(01)第F03424号
Data in this article cite their source and as-of date. Market conditions and regulations change, so check the latest information and consult a professional before deciding. Translated from the Japanese original.