2026 Tax Reform and Real Estate Owners: Revision of Inheritance Tax Valuation for Rental Properties Acquired Within 5 Years
Emi Tokudomi (licensed real estate broker, 宅地建物取引士)Acquisitions
21 min read
Rental apartments and entire apartment buildings often have inheritance tax valuations lower than their purchase prices, which has sometimes been used as an inheritance tax strategy. This valuation method is expected to change for inheritances and gifts occurring on or after January 1, 2027. The revision was indicated in the "Outline of the 2026 Tax Reform" decided by the Cabinet on December 26, 2025, and on September 18, 2026, the National Tax Agency published a concrete draft notice to solicit opinions.
This article organizes what has been confirmed and what remains at the draft stage based on the original texts of the Ministry of Finance's outline and the National Tax Agency's draft notice. It then summarizes the impact on owners holding rental properties acquired within 5 years and the points to check now.
Key Points of This Article
- Rental properties acquired or newly built within 5 years before inheritance or gift will be valued based on "normal transaction price," not on road price (rosenka) or fixed asset tax valuation, as included in the 2026 tax reform outline (Cabinet decision December 26, 2025).
- The National Tax Agency’s draft notice (published September 18, 2026; opinion period until October 18) sets a simplified method applicable to inheritance, legacy, and gift after January 1, 2027, allowing valuation at 80% of the amount calculated based on acquisition price.
- A hypothetical calculation for inheriting an RC building acquired at 200 million yen in about 3 years shows the valuation rising from roughly 105.92 million yen (previous method) to about 159.17 million yen (TLL calculation; assumptions in main text).
What Will Change: Overview of the Revision
The change concerns the method for valuing rental real estate (leased property) for inheritance and gift tax calculation. Currently, land is valued by road price (rosenka), buildings by fixed asset tax valuation, and discounts for rental use (including leased land and rented buildings) are applied. According to the National Tax Agency’s Tax Answer No. 4614 (law as of April 1, 2026), the value of leased land is calculated as "value as owned land minus (value as owned land × leasehold right ratio × tenant right ratio × rental ratio)."
This method can result in valuation significantly lower than market prices. Acquiring rental properties shortly before inheritance to lower valuations has been criticized. The outline states that considering the gap between market price and inheritance tax valuation of leased property, the following two revisions will be implemented:
- Leased real estate acquired or newly built in transactions with consideration within 5 years before the taxation date by the decedent, etc., will be valued at the normal transaction price at the taxation date.
- Leased real estate included in tokenized real estate products such as real estate specified joint ventures or trust beneficiary rights will be valued at the normal transaction price regardless of acquisition date.
This revision will be implemented not through a law amendment but by the issuance of a National Tax Agency notice on property valuation.
Confirmed Matters and Items Still at Draft Stage
As of October 2, 2026, items indicated by the Cabinet-decision outline and those still at the National Tax Agency’s draft notice stage are as follows. The final notice content may change based on the collected opinions.
Items Shown in the Outline (Cabinet Decision December 26, 2025)
- Targets are leased properties acquired or newly built by transactions with consideration within 5 years before the taxation date and tokenized real estate products.
- Valuation is an amount equivalent to the normal transaction price at the taxation date.
- When there is no taxation disadvantage, a simplified method allowing valuation at 80% of the amount calculated based on acquisition price adjusted for land price fluctuations etc. is applicable.
- Applies to assets acquired after January 1, 2027.
- Properties newly built on land held for more than 5 years (including under construction on that date) before the notice is issued are excluded from the 5-year acquisition revision.
Items at the Draft Notice Stage (Published September 18, 2026; Public Comments Until October 18, 2026)
- Specific calculation methods for the 80% simplified valuation (land uses change rate of rosenka; building uses straight-line depreciation expense)
- Scope of exclusions for acquisitions (e.g., acquisitions due to expropriation, property exchange, tax-deferral purchases)
- Definition of "under construction" and the draft date of notice defining transition measures (blank in the draft as "Year 8 month day")
The base date of transition measures is undecided. Owners planning to build rental housing on their land should wait for the notice adoption to confirm conditions.

Valuation Method in the Draft Notice: Valuation at 80% of Acquisition Price-Based Amount
The draft notice states that when the acquisition price is recognized as equivalent to the normal transaction price at acquisition, valuation can be made at 80% of the following amounts:
- Land etc.: Acquisition price × land price fluctuation rate (rosenka at taxation year ÷ rosenka at acquisition year)
- Buildings etc.: Acquisition price minus depreciation expenses from acquisition to taxation date (straight-line method, using statutory useful life; any fraction under one year rounded up)
The acquisition price includes improvement costs and equipment expenses. To illustrate differences with the previous method, a hypothetical calculation was made.
| Item | Previous Valuation Method | Draft Notice Valuation (80% Simplified Method) |
|---|---|---|
| Land (Acquisition price 120 million yen) | 88.2 million yen × (1 − 60% × 30%) = approx. 72.32 million yen | 120 million yen × 1.05 × 80% = 100.8 million yen |
| Building (Acquisition price 80 million yen) | 48 million yen × (1 − 30%) = 33.6 million yen | (80 million yen − 80 million yen × 0.022 × 4 years) × 80% = approx. 58.37 million yen |
| Total | Approx. 105.92 million yen | Approx. 159.17 million yen |
Assumptions (all hypothetical): New RC rental apartment with land acquired in 2026 at 200 million yen, inherited 3 years and 5 months after acquisition, 100% rental ratio. Rosenka rose 5% since acquisition. Previous method assumes land evaluated at 70% of acquisition price × 1.05 × leasehold right ratio 60%, tenant right ratio 30%; building fixed asset tax assessed at 60% of acquisition price. Statutory useful life for RC residential buildings is 47 years (straight-line method depreciation rate 0.022), period rounded up to 4 years. Special deductions for small residential land or debt deductions are not considered. Source: National Tax Agency draft "Valuation of leased property (draft)," Tax Answer Nos. 4602, 4614; TLL calculations.
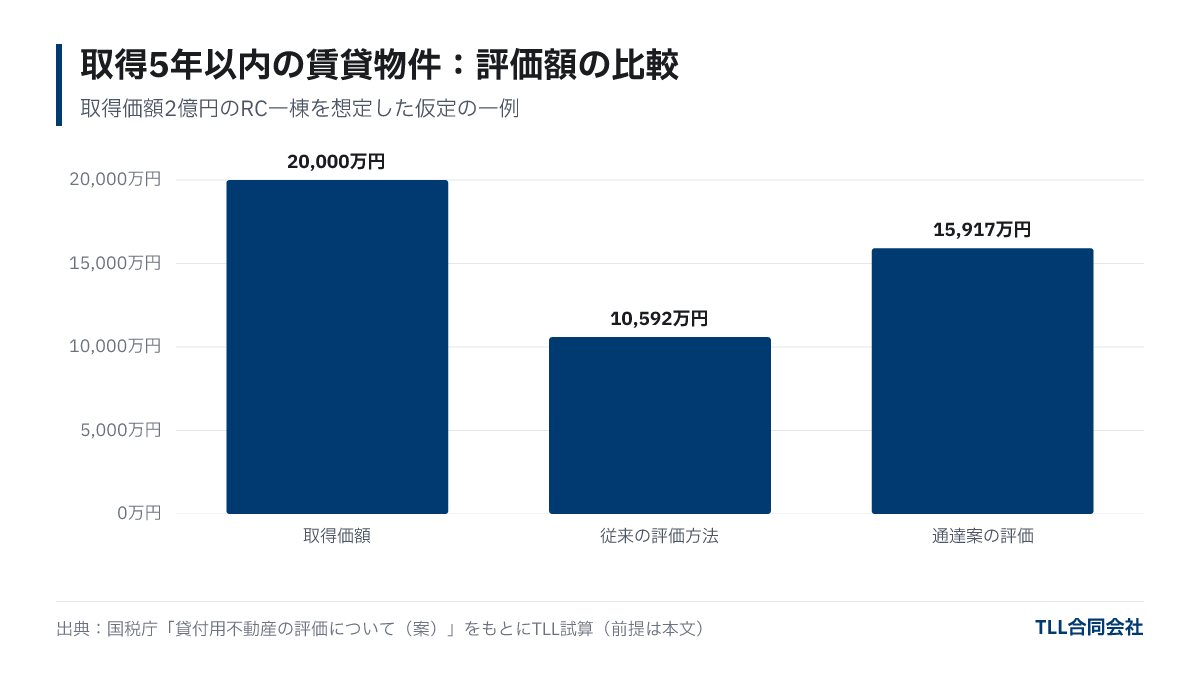
In this assumption, valuation rises approximately 53 million yen. Actual differences will vary greatly depending on the difference between rosenka, fixed asset tax valuation, and purchase price, leasehold ratio, and rental ratio for each property.
Items Not Subject or Subject to Different Rules
According to the draft notice, even rental properties acquired within 5 years have these exceptions or different treatments:
- Properties acquired over 5 years ago: Only acquisitions or new construction within 5 years before taxation date are subject; earlier acquisitions retain previous valuation methods.
- Transition measure new constructions: Buildings newly constructed (including under construction) on land owned for more than 5 years before notice issuance (or obtained by inheritance within 5 years).
- Acquisitions due to expropriation, exchanges, or tax-deferral purchases: Provided certain conditions are met (e.g., transfer price within 120%).
- Building extensions or renovations within 5 years: Extensions or renovations of buildings held for more than 5 years.
- Stock evaluation of corporations: When valuing land and buildings for calculating net asset value of unlisted shares, this rule does not apply as noted.
- Tokenized real estate products: Valued at normal transaction price regardless of acquisition date; other valuation methods such as 90% of principal equivalent are separately indicated.
For corporation-held properties, the valuation method differs from individual owners. Those considering incorporation should consult a tax accountant. General concepts of incorporation are organized in our article on incorporation in apartment management.

Impact on Existing Owners and Confirmation Process
The impact applies to owners of rental properties acquired within 5 years (in principle, the delivery date) who might face inheritance or gift of those properties on or after January 1, 2027. For example, a property purchased in 2023 may be subject to the revision if inherited in 2027 but will revert to previous valuation after 5 years since acquisition. A recommended confirmation flow is as follows.
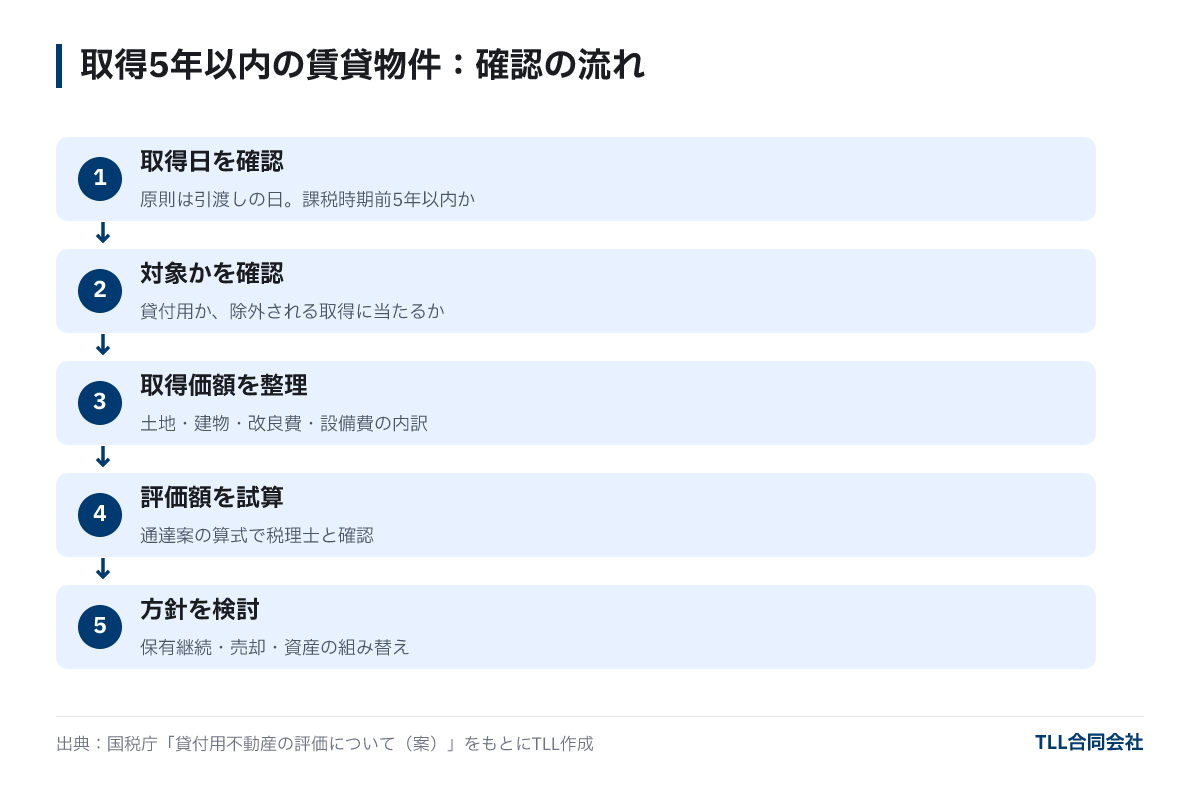
- Confirm acquisition date: Check the delivery date (principal date) from the sales contract or delivery records and list the date 5 years after acquisition.
- Check whether applicable: Confirm if the property is rented and if exclusions or transition measures apply.
- Organize acquisition price: Summarize breakdown of land and building prices plus improvement and equipment costs after purchase.
- Calculate valuation: Use the draft notice formula to estimate valuation differences and review with a tax accountant.
- Consider strategy: Decide whether to hold or sell/restructure assets by comparing inheritance tax, rental income, and capital gains taxes.
When choosing to sell, the “within 5 years” criterion for inheritance tax valuation is separate from the distinction between long-term and short-term capital gains tax (based on ownership over 5 years as of January 1 of the sale year), which also affects net income. See our article on differences between long-term and short-term capital gains tax for details. Current price estimates can be accessed through our free property assessment.
Frequently Asked Questions
Q. From which inheritance does the new valuation apply?
The outline and draft notice specify application to inheritance, legacy, and gift acquisitions on or after January 1, 2027. The notice is still draft, with public comments closing on October 18, 2026.
Q. Will valuation change for apartments bought over 10 years ago?
The revision applies only to properties acquired or newly built within 5 years before the taxation date, so properties acquired 10 years ago are excluded. However, tokenized real estate products are subject regardless of acquisition date.
Q. What about building a new apartment on my own land?
There is a transition measure exempting buildings newly built (including under construction) on land possessed for over 5 years as of the notice issuance date. Since the date is blank in the draft, confirmation is needed after the notice is finalized.
Q. Will valuation equal the purchase price?
The simplified draft method allows valuation at 80% of the acquisition price adjusted for land price movements or depreciation. While not exactly the purchase price, valuations will mostly be higher than the previous method based on rosenka and fixed asset tax valuation.
Summary
- The 2026 tax reform outline (Cabinet decision December 26, 2025) indicates valuing rental real estate acquired or newly built within 5 years before inheritance or gift at normal transaction prices.
- The National Tax Agency draft notice (published September 18, 2026) applies this from inheritance after January 1, 2027, providing a simplified method to value at 80% of acquisition price-based amount. Transition measure base date is undecided.
- Hypothetical calculations for a 200 million yen RC building inherited after about 3 years show valuation rising from about 105.92 million yen to about 159.17 million yen.
- Owners of properties acquired within 5 years should organize acquisition dates and price details, then consult with a tax accountant to estimate valuation after notice finalization.
Featured image (illustration): Photo: Tierra Mallorca / Unsplash
About this article
- Author
- Emi Tokudomi(Acquisitions)Qualifications: Real Estate Transaction Agent
Handles investment property acquisitions and the review of documents and operating figures, drawing on experience in rental management, brokerage and sales support. She has more than 18 years of practical real estate experience and now works on acquisitions at TLL. With Japan's Real Estate Transaction Specialist qualification and bookkeeping knowledge, she considers management and repair costs alongside property income, as well as the documents needed for a transaction. Her articles explain gross versus net yield, purchase costs, financing fundamentals and purchase procedures for foreign nationals. She emphasizes distinguishing advertised yields from the cash left after expenses and identifying what to verify before buying. Her management and brokerage experience informs acquisition assessments that also consider operations after purchase.
View profile → - Publisher
- TLL合同会社宅地建物取引業 東京都知事(1)第108202号住宅宿泊管理業 国土交通大臣(01)第F03424号
Data in this article cite their source and as-of date. Market conditions and regulations change, so check the latest information and consult a professional before deciding. Translated from the Japanese original.